Survey
* Your assessment is very important for improving the work of artificial intelligence, which forms the content of this project
* Your assessment is very important for improving the work of artificial intelligence, which forms the content of this project
Securitization wikipedia , lookup
Investment management wikipedia , lookup
Investment fund wikipedia , lookup
Financial economics wikipedia , lookup
Business valuation wikipedia , lookup
Negative gearing wikipedia , lookup
Global financial system wikipedia , lookup
Global saving glut wikipedia , lookup
Mark-to-market accounting wikipedia , lookup
Capital gains tax in Australia wikipedia , lookup
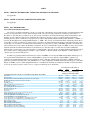
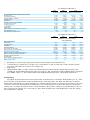
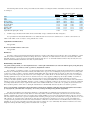
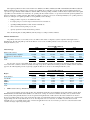
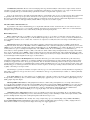
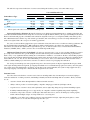
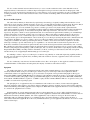
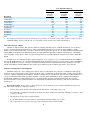
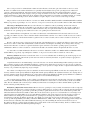
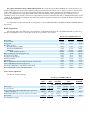
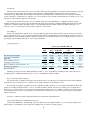
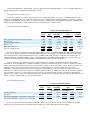
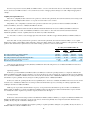
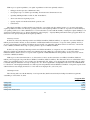
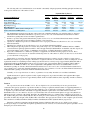
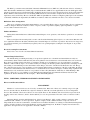
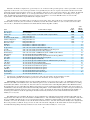
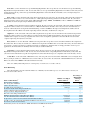
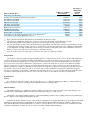
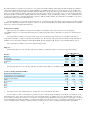
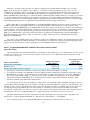
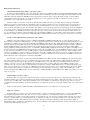
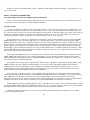
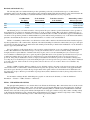
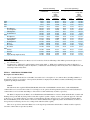
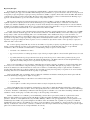
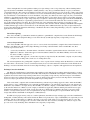
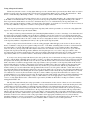
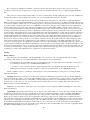
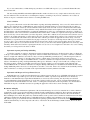
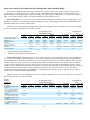
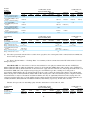
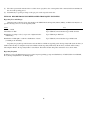
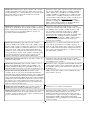
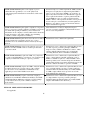
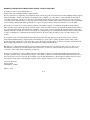
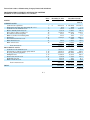
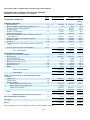
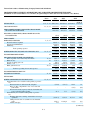
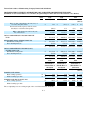
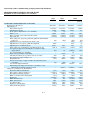
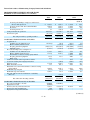
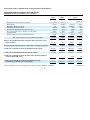
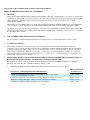
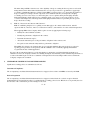
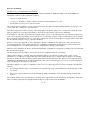
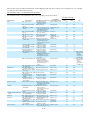
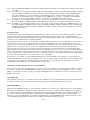
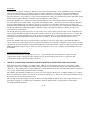
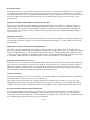
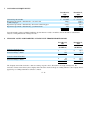
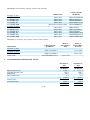
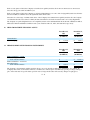
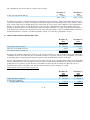
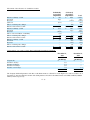
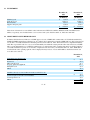
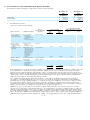
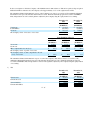
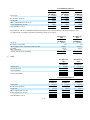
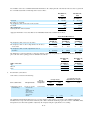
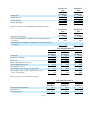
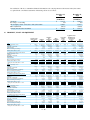
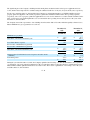
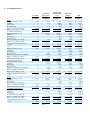
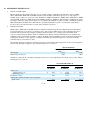
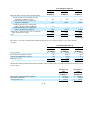
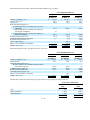
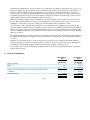
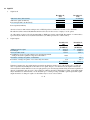
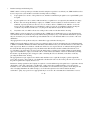
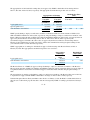
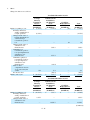
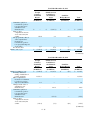
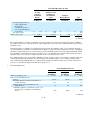
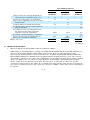
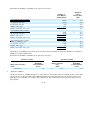
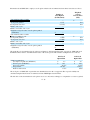
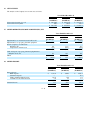
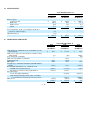
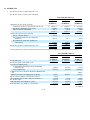
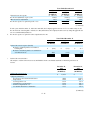
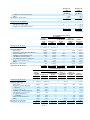
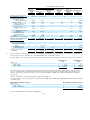
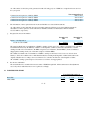
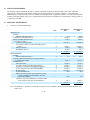
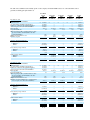
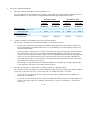
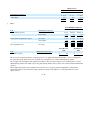
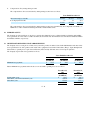
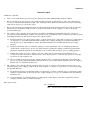
31. INCOME TAX a. Income tax expense recognized in profit or loss Income tax expense consisted of the following: 2012 NT$ (In Millions) Current income tax expense (benefit) Current tax expense recognized in the current year Income tax adjustments on prior years Other income tax adjustments $ Deferred income tax expense (benefit) Effect of tax rate changes The origination and reversal of temporary differences Investment tax credits and operating loss carryforward Income tax expense recognized in profit or loss $ Years Ended December 31 2013 2014 NT$ NT$ (In Millions) (In Millions) 20,637.1 1,440.5 201.1 22,278.7 $ 29,038.2 (2,991.9) (10.6) 26,035.7 $ 49,779.0 (4,417.5) 230.0 45,591.5 (543.6) â â (864.2) 751.0 (427.4) 1,503.8 96.0 22,374.7 $ 5,325.1 6,076.1 32,111.8 $ 2,725.8 2,298.4 47,889.9 A reconciliation of income before income tax and income tax expense recognized in profit or loss was as follows: Income before tax Income tax expense at the statutory rate Tax effect of adjusting items: Nondeductible (deductible) items in determining taxable income Tax-exempt income Additional income tax under the Alternative Minimum Tax Act Additional income tax on unappropriated earnings Effect of tax rate changes on deferred income tax The origination and reversal of temporary differences Income tax credits Remeasurement of investment tax credits Remeasurement of operating loss carryforward 2012 NT$ (In Millions) $ 181,661.1 $ 34,082.8 Years Ended December 31 2013 2014 NT$ NT$ (In Millions) (In Millions) $ 215,961.5 $ 302,073.5 $ 38,539.2 $ 52,766.4 (3,008.6) (9,830.3) (1,498.6) (8,612.0) (1,132.8) (20,415.8) â 9,629.2 (543.6) (864.2) (2,828.3) (4,215.2) (1,688.7) â 14,196.1 â 751.0 (3,137.0) (3,460.9) (1,663.5) 4,081.2 23,771.5 â (427.4) (3,275.1) (3,188.3) (102.3) (Continued) F - 63