
Manager`s Comment Performance Total Return
... as 17% at one point. The sell-off was prompted by further declines in its retail sales; the recovery followed the publication of a letter from an activist investor, Land & Buildings, calling for the company to accelerate the monetisation of its valuable real estate assets. The letter contained no in ...
... as 17% at one point. The sell-off was prompted by further declines in its retail sales; the recovery followed the publication of a letter from an activist investor, Land & Buildings, calling for the company to accelerate the monetisation of its valuable real estate assets. The letter contained no in ...

31-103F1 [F], January 11, 2015
... enterprises. The firm is required to deliver a copy of the executed subordination agreement to the regulator or, in Québec, the securities regulatory authority on the earlier of a) 10 days after the date the agreement is executed or b) the date an amount subordinated by the agreement is excluded fro ...
... enterprises. The firm is required to deliver a copy of the executed subordination agreement to the regulator or, in Québec, the securities regulatory authority on the earlier of a) 10 days after the date the agreement is executed or b) the date an amount subordinated by the agreement is excluded fro ...

form 31-103f1 calculation of excess working capital
... enterprises. The firm is required to deliver a copy of the executed subordination agreement to the regulator or, in Québec, the securities regulatory authority on the earlier of a) 10 days after the date the agreement is executed or b) the date an amount subordinated by the agreement is excluded fro ...
... enterprises. The firm is required to deliver a copy of the executed subordination agreement to the regulator or, in Québec, the securities regulatory authority on the earlier of a) 10 days after the date the agreement is executed or b) the date an amount subordinated by the agreement is excluded fro ...

Managerial Objective - BYU Marriott School
... • There are tradeoffs in balancing compensation risks: – Increasing total wealth leverage to align managers’ interests more closely with investors’ interests increases retention risk if the market turns down for reasons managers cannot control. It also increases shareholder cost in good times that, ...
... • There are tradeoffs in balancing compensation risks: – Increasing total wealth leverage to align managers’ interests more closely with investors’ interests increases retention risk if the market turns down for reasons managers cannot control. It also increases shareholder cost in good times that, ...

FAIR VALUE IN FINANCIAL STATEMENTS – ADVANTAGES AND
... reliability. If the fair value of an asset follows the development of a market environment, this means that the value of an asset changes with the market. If the market with regards to the nature of a given asset booms, the price of a given asset goes up; if it busts, the price goes down too. A vola ...
... reliability. If the fair value of an asset follows the development of a market environment, this means that the value of an asset changes with the market. If the market with regards to the nature of a given asset booms, the price of a given asset goes up; if it busts, the price goes down too. A vola ...


PPT chapter 12
... balance sheets, profit and loss statements and cash flow statements should be prepared. • Key financial ratios can then be calculated to monitor the state of the business and its ability to maintain operations and aid in the decision-making ...
... balance sheets, profit and loss statements and cash flow statements should be prepared. • Key financial ratios can then be calculated to monitor the state of the business and its ability to maintain operations and aid in the decision-making ...

Updating Accounting Standards
... In accordance with this announcement, the government is proposing to update section 76 of the General Regulation of the Pension Benefits Act (PBA) to reflect updates to the Chartered Professional Accountant (CPA) Canada Handbook, previously referred to as the Canadian Institute of Chartered Accounta ...
... In accordance with this announcement, the government is proposing to update section 76 of the General Regulation of the Pension Benefits Act (PBA) to reflect updates to the Chartered Professional Accountant (CPA) Canada Handbook, previously referred to as the Canadian Institute of Chartered Accounta ...

mfin202sampletest2
... C. 1. What dividend yield would be reported in the financial press for a stock that currently pays a $1 dividend per quarter and the most recent stock price was $40? A. 2.5% B. 4.0% C. 10.0% D. 15.0% B. 2. Which of the following observations provides evidence against strong-form market efficiency? A ...
... C. 1. What dividend yield would be reported in the financial press for a stock that currently pays a $1 dividend per quarter and the most recent stock price was $40? A. 2.5% B. 4.0% C. 10.0% D. 15.0% B. 2. Which of the following observations provides evidence against strong-form market efficiency? A ...

New Financial Regulator Seen to Target Chaebol
... accurate and timely information for investors. There is also further scope for improvement which we hope Korea will look into.’’ ...
... accurate and timely information for investors. There is also further scope for improvement which we hope Korea will look into.’’ ...
What is Investing? - Undergraduate Investment Society at UCLA
... •Originally used to refer financial instruments secured by an asset. •In modern use, it can refer to all financial instruments regardless of if they are secured. ...
... •Originally used to refer financial instruments secured by an asset. •In modern use, it can refer to all financial instruments regardless of if they are secured. ...

the accounting process
... The data is then recorded in chronological order in a ledger and classified by account ...
... The data is then recorded in chronological order in a ledger and classified by account ...
Chapter 1 - Practice Questions 1. Financial assets
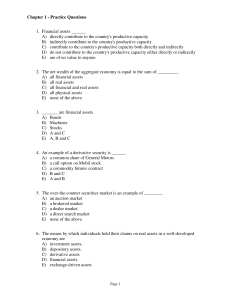
... C) contribute to the country's productive capacity both directly and indirectly D) do not contribute to the country's productive capacity either directly or indirectly E) are of no value to anyone 2. The net wealth of the aggregate economy is equal to the sum of _________. A) all financial assets B) ...
... C) contribute to the country's productive capacity both directly and indirectly D) do not contribute to the country's productive capacity either directly or indirectly E) are of no value to anyone 2. The net wealth of the aggregate economy is equal to the sum of _________. A) all financial assets B) ...

Fair value of financial instruments Amortized cost of financial
... The Allianz Group applies the IAS 39 fair value measurement rules to determine the fair value of financial instruments. Active markets – quoted market price The fair values of financial instruments that are traded in active markets are based on quoted market prices or dealer price quotations on th ...
... The Allianz Group applies the IAS 39 fair value measurement rules to determine the fair value of financial instruments. Active markets – quoted market price The fair values of financial instruments that are traded in active markets are based on quoted market prices or dealer price quotations on th ...

1 Should Financial Institutions Mark to Market?
... move of the International Accounting Standards Board (IASB) and the U.S. Financial Accounting Standards Board (FASB) to make changes in this direction as part of an attempt to standardize accounting standards across countries. The debate has two opposing views. On the one hand, mark-to-market accoun ...
... move of the International Accounting Standards Board (IASB) and the U.S. Financial Accounting Standards Board (FASB) to make changes in this direction as part of an attempt to standardize accounting standards across countries. The debate has two opposing views. On the one hand, mark-to-market accoun ...


ALPHA BITES Rovers Return? - Alpha Portfolio Management
... Avoiding the ‘mines in the minefield’ is just as important as picking the winners at the moment. We continue to focus on businesses with strong cash flow given that these can weather challenging trading conditions and are more likely to attract the attention of potential acquirers if business confid ...
... Avoiding the ‘mines in the minefield’ is just as important as picking the winners at the moment. We continue to focus on businesses with strong cash flow given that these can weather challenging trading conditions and are more likely to attract the attention of potential acquirers if business confid ...

CHAPTER 13:Financial Instruments: Long Term Debt
... investors will be willing to pay more than the face value (a premium) to acquire the bond. A bond may offer an interest rate different from the market rate, as the bond terms are set in advance of the actual issue date. For a bond to sell at par, the effective rate and the nominal rate must be the s ...
... investors will be willing to pay more than the face value (a premium) to acquire the bond. A bond may offer an interest rate different from the market rate, as the bond terms are set in advance of the actual issue date. For a bond to sell at par, the effective rate and the nominal rate must be the s ...

E-Commerce and Accounting Principles
... Roadmap for the removal for the reconciliation requirement for non-US companies that use IFRS and are registered in the United States. Committee of European Securities Regulators to identify area for improvement of accounting standard.” “First, the Boards will reach a conclusion about whether major ...
... Roadmap for the removal for the reconciliation requirement for non-US companies that use IFRS and are registered in the United States. Committee of European Securities Regulators to identify area for improvement of accounting standard.” “First, the Boards will reach a conclusion about whether major ...


Ethical and Educational Perspectives of Accounting Practices: Experience with Two Canadian Service Organizations:
... literature in oredr to regain the trust in the accounting profession and to prevent future scandals. The purpose of this research is to investigate the influence of education and work background of accountants on their perspective on ethics. This explorative case study is carried out within the fram ...
... literature in oredr to regain the trust in the accounting profession and to prevent future scandals. The purpose of this research is to investigate the influence of education and work background of accountants on their perspective on ethics. This explorative case study is carried out within the fram ...

Meeting Highlights - Private Company Financial Reporting Committee
... of cost method equity investments as described in Topic 320 of the FASB Codification. Also, FASB staff asked Committee members if the current impairment guidance for nonmarketable equity securities needs improvement, if changes are needed to the accounting for equity-method investments, and if they ...
... of cost method equity investments as described in Topic 320 of the FASB Codification. Also, FASB staff asked Committee members if the current impairment guidance for nonmarketable equity securities needs improvement, if changes are needed to the accounting for equity-method investments, and if they ...

What is the Balance Sheet?
... • It is a report of a firm’s activities during a given period of time • It shows revenue and expenses of the firm, the effect of interest and tax, and the net income for the period ...
... • It is a report of a firm’s activities during a given period of time • It shows revenue and expenses of the firm, the effect of interest and tax, and the net income for the period ...