
Questions on subsections 1/2/3/5 of Chapter 41E Section 8
... clearly state what assets are considered to be admissible in covering the liabilities. It is noted that Chapter 41G of the Ordinance contains regulations on the valuation of assets, but it applies only to general insurance business, and not to life business. The Insurance Authority (“IA”) adopts a p ...
... clearly state what assets are considered to be admissible in covering the liabilities. It is noted that Chapter 41G of the Ordinance contains regulations on the valuation of assets, but it applies only to general insurance business, and not to life business. The Insurance Authority (“IA”) adopts a p ...
Notes to Consolidated Financial Statements
... basis of assets and liabilities is based on amounts that meet the recognition threshold and are measured in accordance with current standards. We provide valuation allowances against the deferred tax assets for which the realization is uncertain. We review these items regularly in light of changes i ...
... basis of assets and liabilities is based on amounts that meet the recognition threshold and are measured in accordance with current standards. We provide valuation allowances against the deferred tax assets for which the realization is uncertain. We review these items regularly in light of changes i ...
Comparative Analysis of Blue Chip Fund
... Net asset value (NAV) is the value of an entity's assets minus the value of its liabilities, often in relation to open-end or mutual funds, since shares of such funds registered with the U.S. Securities and Exchange Commission are redeemed at their net asset value. This may also be the same as the b ...
... Net asset value (NAV) is the value of an entity's assets minus the value of its liabilities, often in relation to open-end or mutual funds, since shares of such funds registered with the U.S. Securities and Exchange Commission are redeemed at their net asset value. This may also be the same as the b ...

Traditional Investment Alternatives (cont`d)
... • Match potential investments with your goals in terms of several factors – Safety and risk • Minimizing the risk of loss (e.g., investing in blue-chip stocks) • Maximizing potential returns by assuming some risk ...
... • Match potential investments with your goals in terms of several factors – Safety and risk • Minimizing the risk of loss (e.g., investing in blue-chip stocks) • Maximizing potential returns by assuming some risk ...

Investor Sentiment and Price Predictability in the Oil Future Market
... It is more likely to happen that sentiment affect upcoming price movements when the market sentiment is bullish rather than when the market sentiment is normal Examining when the sentiment is suspected to be bullish - Retrieve sentiment level that is higher than the average level over the sample per ...
... It is more likely to happen that sentiment affect upcoming price movements when the market sentiment is bullish rather than when the market sentiment is normal Examining when the sentiment is suspected to be bullish - Retrieve sentiment level that is higher than the average level over the sample per ...

Factsheet Total Emerging Markets Fund Class I USD
... ranking. For periods not shown, Morningstar does not provide rankings based on synthetic performance. Key Risks: The fund is actively managed and its characteristics will vary. Stock values fluctuate in price so the value of your investment can go down depending on market conditions. International i ...
... ranking. For periods not shown, Morningstar does not provide rankings based on synthetic performance. Key Risks: The fund is actively managed and its characteristics will vary. Stock values fluctuate in price so the value of your investment can go down depending on market conditions. International i ...

Disclaimer
... offer to sell or a solicitation of an offer to buy the securities referred to herein. Investors should note that values of such securities, if any, may fluctuate and that each security’s price or value may rise or fall. Opinions or recommendations contained herein are in form of technical ratings an ...
... offer to sell or a solicitation of an offer to buy the securities referred to herein. Investors should note that values of such securities, if any, may fluctuate and that each security’s price or value may rise or fall. Opinions or recommendations contained herein are in form of technical ratings an ...

Chapter 1, Answer to Questions
... Derivative securities are securities derived from debt or equity securities and structured to exhibit characteristics different from the underlying securities. Options are derivative securities that allow an investor to sell or buy another security or asset at a specific price over a given time peri ...
... Derivative securities are securities derived from debt or equity securities and structured to exhibit characteristics different from the underlying securities. Options are derivative securities that allow an investor to sell or buy another security or asset at a specific price over a given time peri ...

Risk Free Discount Rates under AASB 1038 1
... This note was prepared by the Valuation Standard Review Task Force (TF) of the Institute of Actuaries of Australia (“IAAust”) in February 2005. This discussion note does not represent a professional standard or a guidance note of the IAAust and it has been prepared for the purposes of generating dis ...
... This note was prepared by the Valuation Standard Review Task Force (TF) of the Institute of Actuaries of Australia (“IAAust”) in February 2005. This discussion note does not represent a professional standard or a guidance note of the IAAust and it has been prepared for the purposes of generating dis ...

Franklin Templeton Emerging Market Debt Opportunities
... Effective with the third quarter of 2008, composite returns in base currency are translated to other currencies using London FX rates instead of New York rates for all time periods presented, which may result in revisions to multi-currency returns compared to what was previously reported for prior p ...
... Effective with the third quarter of 2008, composite returns in base currency are translated to other currencies using London FX rates instead of New York rates for all time periods presented, which may result in revisions to multi-currency returns compared to what was previously reported for prior p ...

The production of financial corporations and price/volume
... of the financial assets and liabilities to which FISIM applies. A single rate should be used for transactions in the local currency, whereas different rates may be used for transactions in other currencies. ...
... of the financial assets and liabilities to which FISIM applies. A single rate should be used for transactions in the local currency, whereas different rates may be used for transactions in other currencies. ...

Accrued Interest on Debt Securities with a Fixed Rate of
... or when it is paid for. The same applies to income: “Under investment income, interest is recorded on an accrual basis, which is the continuous method of recording that matches the cost of capital with the provision of capital. If the interest is not actually paid, an entry is required, together wit ...
... or when it is paid for. The same applies to income: “Under investment income, interest is recorded on an accrual basis, which is the continuous method of recording that matches the cost of capital with the provision of capital. If the interest is not actually paid, an entry is required, together wit ...

National wealth, land values and monetary policy
... The first is that according to the ABS’ latest estimates, the total value of Australia’s assets as at end June 2014 was around $12½ trillion, or around $500,000 for each person living in Australia. After an adjustment is made for net foreign liabilities, the net asset position, or net wealth, was ar ...
... The first is that according to the ABS’ latest estimates, the total value of Australia’s assets as at end June 2014 was around $12½ trillion, or around $500,000 for each person living in Australia. After an adjustment is made for net foreign liabilities, the net asset position, or net wealth, was ar ...

Chapter 14
... Traditional cash flow equals net income plus depreciation expense and deferred taxes Also adjust for changes in operating assets and liabilities that use or provide cash ...
... Traditional cash flow equals net income plus depreciation expense and deferred taxes Also adjust for changes in operating assets and liabilities that use or provide cash ...

Bombay Stock Exchange Limited
... The company which has received in-principle approval from the recognised stock exchange for listing of its specified securities on the institutional trading platform shall be deemed to have been waived by the Board under sub-rule (7) of rule 19 from clause (b) of sub-rule (2) of rule 19 of Securitie ...
... The company which has received in-principle approval from the recognised stock exchange for listing of its specified securities on the institutional trading platform shall be deemed to have been waived by the Board under sub-rule (7) of rule 19 from clause (b) of sub-rule (2) of rule 19 of Securitie ...


BT Core Hedged Global Share Fund
... Performance returns are calculated net of ICR (Management Fees) and pre tax. Past performance is not a reliable indicator of future performance, the value of your investment can go up and down. Performance figures are calculated in accordance with the Financial Services Council (FSC) standards. Tota ...
... Performance returns are calculated net of ICR (Management Fees) and pre tax. Past performance is not a reliable indicator of future performance, the value of your investment can go up and down. Performance figures are calculated in accordance with the Financial Services Council (FSC) standards. Tota ...
Chapter 4
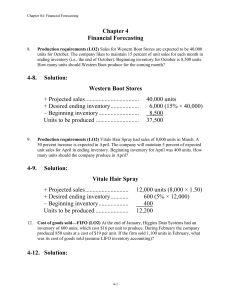
... The company makes 10 percent of its sales for cash and 90 percent on credit. Of the credit sales, 20 percent are collected in the month after the sale and 80 percent are collected two months later. Archer pays for 40 percent of its purchases in the month after purchase and 60 percent two months afte ...
... The company makes 10 percent of its sales for cash and 90 percent on credit. Of the credit sales, 20 percent are collected in the month after the sale and 80 percent are collected two months later. Archer pays for 40 percent of its purchases in the month after purchase and 60 percent two months afte ...


Upcoming changes to the BMO Money Market Funds
... Money Market Funds as listed below: BMO Prime Money Market Fund BMO Tax-Free Money Market Fund BMO Government Money Market Fund All three of these funds will continue to maintain a stable net asset value (NAV) of $1.00 by utilizing the amortized cost method to value portfolio securities in accordanc ...
... Money Market Funds as listed below: BMO Prime Money Market Fund BMO Tax-Free Money Market Fund BMO Government Money Market Fund All three of these funds will continue to maintain a stable net asset value (NAV) of $1.00 by utilizing the amortized cost method to value portfolio securities in accordanc ...

IFRS 9 Financial Instruments
... An option* whose strike price* is equal to the current, prevailing price in the underlying cash spot*market. At-the-money forward An option* whose strike price* is equal to the current, prevailing price in the underlying forward market. Available-for-sale financial assets Those financial assets* tha ...
... An option* whose strike price* is equal to the current, prevailing price in the underlying cash spot*market. At-the-money forward An option* whose strike price* is equal to the current, prevailing price in the underlying forward market. Available-for-sale financial assets Those financial assets* tha ...


The Theoretical and Empirical Study of Marketing Opportunities
... nature. It is precisely because of these complex features, making the academic theory of marketing opportunities for the systematic study of extreme deprivation. Search literature at home and abroad found that few studies conducted the meaning of marketing opportunities, in which a few representativ ...
... nature. It is precisely because of these complex features, making the academic theory of marketing opportunities for the systematic study of extreme deprivation. Search literature at home and abroad found that few studies conducted the meaning of marketing opportunities, in which a few representativ ...

Question 1 All of the following are reported as current liabilities
... a revenue account. a contra account to Rental Revenue. Question 9 The amount of sales tax collected by a retail store when making sales is a miscellaneous revenue for the store. a current liability. not recorded because it is a tax paid by the customer. recorded as an operating expense Question 10 ...
... a revenue account. a contra account to Rental Revenue. Question 9 The amount of sales tax collected by a retail store when making sales is a miscellaneous revenue for the store. a current liability. not recorded because it is a tax paid by the customer. recorded as an operating expense Question 10 ...