Chapter 9 Notes
... Journal entries recorded to update general ledger accounts at the end of a fiscal period. Adjusting entries are recorded on the page following the page on which the last daily transactions for the month are recorded. Adjusting entries are obtained from the adjustment column of the WS. The heading, A ...
... Journal entries recorded to update general ledger accounts at the end of a fiscal period. Adjusting entries are recorded on the page following the page on which the last daily transactions for the month are recorded. Adjusting entries are obtained from the adjustment column of the WS. The heading, A ...

Terms of Reference of ISWGNA Task Force on FISIM
... Drafting of the Handbook was initiated in 2004 as part of the United Nations series of handbooks on national accounts ...
... Drafting of the Handbook was initiated in 2004 as part of the United Nations series of handbooks on national accounts ...


The role of a financial transaction tax in sustainable finance
... transaction tax successfully achieve this goal? We need to take a closer look at the current derivatives market to answer this question. Korean taxation on finance – financial income tax, capital gains tax, securities transaction tax Starting in 2013, the government strengthened the tax system and ...
... transaction tax successfully achieve this goal? We need to take a closer look at the current derivatives market to answer this question. Korean taxation on finance – financial income tax, capital gains tax, securities transaction tax Starting in 2013, the government strengthened the tax system and ...

The Economic Value of ESG/SRI
... associated with an increase in the attention to governance by a wide range of market participants; • Until the beginning of the 2000s, stock market reactions to earning announcements reflected the market’s being more positively surprised by the earning announcements of good-governance firms than by ...
... associated with an increase in the attention to governance by a wide range of market participants; • Until the beginning of the 2000s, stock market reactions to earning announcements reflected the market’s being more positively surprised by the earning announcements of good-governance firms than by ...


The TAMRIS Consultancy - Money Managed Properly
... individual, profitably and efficiently? Personalising a portfolio to an individual’s financial needs over time is complex without the sophisticated systems that manage the thousands of calculations that have to be done every time a portfolio is constructed or managed and every time relative market a ...
... individual, profitably and efficiently? Personalising a portfolio to an individual’s financial needs over time is complex without the sophisticated systems that manage the thousands of calculations that have to be done every time a portfolio is constructed or managed and every time relative market a ...

Do Accounting Changes Affect the Economic Behavior of Financial
... TPS after these accounting changes makes this a good setting to examine whether accounting changes induce changes in banks economic behavior even when regulatory capital effects are deminimus. To mitigate concerns that observed changes might be driven by changes in the demand for TPS, I examine how ...
... TPS after these accounting changes makes this a good setting to examine whether accounting changes induce changes in banks economic behavior even when regulatory capital effects are deminimus. To mitigate concerns that observed changes might be driven by changes in the demand for TPS, I examine how ...

Poplar Forest Cornerstone Fund Summary Prospectus
... Equity securities in which the Fund may invest include, but are not limited to, common stocks, foreign equity securities, convertible securities, and options on stocks, warrants, rights, and/or other investment companies, including mutual funds and exchange-traded funds (“ETFs”). Equity securities w ...
... Equity securities in which the Fund may invest include, but are not limited to, common stocks, foreign equity securities, convertible securities, and options on stocks, warrants, rights, and/or other investment companies, including mutual funds and exchange-traded funds (“ETFs”). Equity securities w ...


Snímek 1
... people are comfortable with, and the intermediaries then use the funds they acquire by selling these assets to purchase other assets that may have far more risk ...
... people are comfortable with, and the intermediaries then use the funds they acquire by selling these assets to purchase other assets that may have far more risk ...
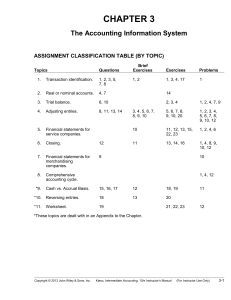
chap.3 - HCC Learning Web
... Depending on time constraints and students’ accounting course background, Chapter 3 can be approached in several different ways: (1) Spend 2-3 class sessions reviewing the chapter and Appendices 3-A through 3-C. (2) Spend 1-2 class sessions reviewing selected portions of the chapter and Appendix 3-A ...
... Depending on time constraints and students’ accounting course background, Chapter 3 can be approached in several different ways: (1) Spend 2-3 class sessions reviewing the chapter and Appendices 3-A through 3-C. (2) Spend 1-2 class sessions reviewing selected portions of the chapter and Appendix 3-A ...

Theory of speculative bubble
... Speculates are happy if won and if the winning was based on calculation that was despite of the others expectation correct. The fact that their calculation was correct is for them more satisfy that the money they earned. But players are different. They boasted about they winning but they were sile ...
... Speculates are happy if won and if the winning was based on calculation that was despite of the others expectation correct. The fact that their calculation was correct is for them more satisfy that the money they earned. But players are different. They boasted about they winning but they were sile ...

McGraw-Hill/Irwin
... marginal tax rates? Which should we use when making financial decisions? • How do we determine a firm’s cash flows? What are the equations and where do we find the information? ...
... marginal tax rates? Which should we use when making financial decisions? • How do we determine a firm’s cash flows? What are the equations and where do we find the information? ...

The Stock Market: What Does it Do and How Has It Performed
... This graphic highlights the best and worst annualized performance for each holding period from 1950 – 1996. It shows that there is less risk of a low or negative return when a portfolio of S&P 500 stocks is held for a longer period of time. Jump to first page ...
... This graphic highlights the best and worst annualized performance for each holding period from 1950 – 1996. It shows that there is less risk of a low or negative return when a portfolio of S&P 500 stocks is held for a longer period of time. Jump to first page ...

Let`s Suppose... - Franklin Templeton Investments
... This measure takes into account variations in a fund’s monthly performance, and does not take into account the effects of sales charges, placing more emphasis on downward variations and rewarding consistent performance. The top 10% of funds in each category receive 5 stars, the next 22.5% receive 4 ...
... This measure takes into account variations in a fund’s monthly performance, and does not take into account the effects of sales charges, placing more emphasis on downward variations and rewarding consistent performance. The top 10% of funds in each category receive 5 stars, the next 22.5% receive 4 ...

Materials Management System
... ◦◦ Values by specific cost, average cost or standard costing methods. ◦◦ Tracks capital and expense items and third-party leased equipment. ◦◦ Assigns unlimited additional costs (freight, duty, tax) to inventory value. ◦◦ Issues by Bill of Material. ◦◦ Automatically creates electronic material requi ...
... ◦◦ Values by specific cost, average cost or standard costing methods. ◦◦ Tracks capital and expense items and third-party leased equipment. ◦◦ Assigns unlimited additional costs (freight, duty, tax) to inventory value. ◦◦ Issues by Bill of Material. ◦◦ Automatically creates electronic material requi ...

Chapter 6 - Fund Accounting
... There is no limit on the number of individual funds a LUA may use for accounting and financial reporting purposes. In practice, a single LUA can have anywhere from ten or fewer funds to dozens of individual funds. Nonetheless, it is a basic principle of governmental accounting that LUAs should use t ...
... There is no limit on the number of individual funds a LUA may use for accounting and financial reporting purposes. In practice, a single LUA can have anywhere from ten or fewer funds to dozens of individual funds. Nonetheless, it is a basic principle of governmental accounting that LUAs should use t ...

Baltic Property Fund Quarterly Report April - June 2016
... Interest costs totalled EUR 1.7m for the financial year and have decreased by 12% compared to the same period last year, benefitting from negative floating rates on the market. Net profit for the financial year 2015/16 amounts to EUR 6.5m (EUR 5.0m if excluding property revaluation). The investment ...
... Interest costs totalled EUR 1.7m for the financial year and have decreased by 12% compared to the same period last year, benefitting from negative floating rates on the market. Net profit for the financial year 2015/16 amounts to EUR 6.5m (EUR 5.0m if excluding property revaluation). The investment ...

Chapter Twenty - Cengage Learning
... monitors the market value of particular stocks and enters buy or sell orders when those stocks reach ...
... monitors the market value of particular stocks and enters buy or sell orders when those stocks reach ...
CHAPTER 10 PLANT ASSETS, NATURAL RESOURCES, AND
... depreciation does not result in an accumulation of cash for the replacement of the asset. Land is the only plant asset that is not depreciated. ...
... depreciation does not result in an accumulation of cash for the replacement of the asset. Land is the only plant asset that is not depreciated. ...

2003 Report as a word document
... scheme are held in trust administered funds. The pension cost relating to the scheme is assessed in accordance with the advice of a qualified independent actuary using a market-based valuation method. The pension cost for the scheme was £7,601,000 which includes £4,354,000 in respect of the amortisa ...
... scheme are held in trust administered funds. The pension cost relating to the scheme is assessed in accordance with the advice of a qualified independent actuary using a market-based valuation method. The pension cost for the scheme was £7,601,000 which includes £4,354,000 in respect of the amortisa ...