
Chapter 1 - Testbankster.com
... 8. Define some defensive measures used by target firms to avoid a takeover. Are these measures beneficial for shareholders? 9. Explain the potential advantages of a stock acquisition over an asset acquisition. 10. Explain the difference between an accretive and a dilutive acquisition. 11. Describe t ...
... 8. Define some defensive measures used by target firms to avoid a takeover. Are these measures beneficial for shareholders? 9. Explain the potential advantages of a stock acquisition over an asset acquisition. 10. Explain the difference between an accretive and a dilutive acquisition. 11. Describe t ...


Research on the Stock Market Response to Earnings - PUC-SP
... Rit of all groups approaches to point 0. Group (-∞,-20), [-4,-2), [0.5,2) and [20,+∞) are described as: Curve for Group (-∞,-20) is close to 0.4 in 20 days before the publishing date of accounting report. It starts to rise upward in 10 days before the publishing date and maximum up to 0.4. After the ...
... Rit of all groups approaches to point 0. Group (-∞,-20), [-4,-2), [0.5,2) and [20,+∞) are described as: Curve for Group (-∞,-20) is close to 0.4 in 20 days before the publishing date of accounting report. It starts to rise upward in 10 days before the publishing date and maximum up to 0.4. After the ...
Financial statements
... The objective of this Standard is to prescribe the classification, disclosure and accounting treatment of certain items in the income statement so that all enterprises prepare and present an income statement on a consistent basis. Accordingly, this Standard requires the classification and disclosure ...
... The objective of this Standard is to prescribe the classification, disclosure and accounting treatment of certain items in the income statement so that all enterprises prepare and present an income statement on a consistent basis. Accordingly, this Standard requires the classification and disclosure ...


HSI 12.31.16 - Stmt of Fin Condition
... Income Taxes We are included in HNAH's consolidated federal income tax return and in various combined state income tax returns. As such, we have entered into a tax allocation agreement with HNAH and its subsidiary entities (the "HNAH Group") included in the consolidated return which governs the curr ...
... Income Taxes We are included in HNAH's consolidated federal income tax return and in various combined state income tax returns. As such, we have entered into a tax allocation agreement with HNAH and its subsidiary entities (the "HNAH Group") included in the consolidated return which governs the curr ...


Price-Level Accounting, Full Disclosure, and Rule 10b-5
... supplemental statements would be mandatory for all businesses that desire to have their financial statements certified as in accordance with generally accepted accounting principles. 19 The FASB proposal's response to inflation is not the only one possible. An alternative is to adjust asset figures ...
... supplemental statements would be mandatory for all businesses that desire to have their financial statements certified as in accordance with generally accepted accounting principles. 19 The FASB proposal's response to inflation is not the only one possible. An alternative is to adjust asset figures ...
LO 5 - Test Banks Shop
... historical cost on all balance sheets until the company disposes of them since cost is objective, or verifiable by an outside observer Certain assets are valued on subsequent balance sheets at market value if the amount can be objectively determined Use price asset could be sold for, rather than ...
... historical cost on all balance sheets until the company disposes of them since cost is objective, or verifiable by an outside observer Certain assets are valued on subsequent balance sheets at market value if the amount can be objectively determined Use price asset could be sold for, rather than ...

chapter 27 powerpoint abridged for students
... investment falls when the interest rate rises. THE BASIC TOOLS OF FINANCE ...
... investment falls when the interest rate rises. THE BASIC TOOLS OF FINANCE ...

F. Peter Boer[*] - Tiger Scientific Inc
... A part of the crisis in valuation arose from the growing differences between market value and the accountant’s perspective of valuation based on historical cost. While this circumstance could, in principle, have resulted from smart management delivering superior cash flows, this explanation did not ...
... A part of the crisis in valuation arose from the growing differences between market value and the accountant’s perspective of valuation based on historical cost. While this circumstance could, in principle, have resulted from smart management delivering superior cash flows, this explanation did not ...
Exam Name___________________________________ TRUE
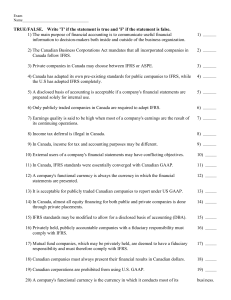
... 36) The CPA Canada Handbook requires that income for tax purposes be equal to a company's accounting income at all times. ...
... 36) The CPA Canada Handbook requires that income for tax purposes be equal to a company's accounting income at all times. ...


Explanatory Notes - Central Bank of Nigeria
... The "Current Transfers" is the fourth sub-account under the Current Account. It is a unilateral transfer by the reporting economy to the ROW or vice versa without an equivalent value in exchange. It is usually classified as private (other sector) or official (government). Private transfers include ...
... The "Current Transfers" is the fourth sub-account under the Current Account. It is a unilateral transfer by the reporting economy to the ROW or vice versa without an equivalent value in exchange. It is usually classified as private (other sector) or official (government). Private transfers include ...

BT 325
... Kieso, Weygandt and Warfield, Intermediate Accounting, 12th edition, 2007. Class Notes Learning Goals: Enhance your understanding of corporate financial reporting and generally accepted accounting principles so you can Appreciate how GAAP impact information reported in the financial statements I ...
... Kieso, Weygandt and Warfield, Intermediate Accounting, 12th edition, 2007. Class Notes Learning Goals: Enhance your understanding of corporate financial reporting and generally accepted accounting principles so you can Appreciate how GAAP impact information reported in the financial statements I ...

aia-qb
... (vi) The company’s Finance Director decides to make a provision for the value of the brands owned by the company on the asset side of the balance sheet. (vii) The President of a successful company, who has been responsible for marketing strategy, suddenly passes away. (3) On the 1st May the share pr ...
... (vi) The company’s Finance Director decides to make a provision for the value of the brands owned by the company on the asset side of the balance sheet. (vii) The President of a successful company, who has been responsible for marketing strategy, suddenly passes away. (3) On the 1st May the share pr ...

F2012C00294 F2012C00294
... section 1020B products must, when making the request, inform the licensee that the sale is a short sale to which this section applies. (3) A financial services licensee who is a participant on the market must, before selling section 1020B products on behalf of another person, ask the other person wh ...
... section 1020B products must, when making the request, inform the licensee that the sale is a short sale to which this section applies. (3) A financial services licensee who is a participant on the market must, before selling section 1020B products on behalf of another person, ask the other person wh ...
Financial Statements for the period ending November
... Loans and receivables are initially recognized at the transaction value and subsequently carried at amortized cost less impairment losses. The impairment loss on receivables is based on a review of all outstanding amounts at year-end. Bad debts are written off during the year in which they are ident ...
... Loans and receivables are initially recognized at the transaction value and subsequently carried at amortized cost less impairment losses. The impairment loss on receivables is based on a review of all outstanding amounts at year-end. Bad debts are written off during the year in which they are ident ...

Слайд 1 - Beltelecom
... Foreign currency and assets acquired for foreign currency, receivables and payables are reported at the National Bank exchange rate in effect on the business transaction date of regular accounting. ...
... Foreign currency and assets acquired for foreign currency, receivables and payables are reported at the National Bank exchange rate in effect on the business transaction date of regular accounting. ...
Implications of Implementation of IAS 41 about Agriculture on
... to produce, not for sale in the short term period. For biological asset available for sale (example: cattle), the value is easier to get in the market. Biological asset available for sale is classified as inventory. Fair value of biological assets that is intended to produce, such as cows, milk-prod ...
... to produce, not for sale in the short term period. For biological asset available for sale (example: cattle), the value is easier to get in the market. Biological asset available for sale is classified as inventory. Fair value of biological assets that is intended to produce, such as cows, milk-prod ...

Monetizing Life Science Company Net Operating Losses
... investor losses. In some circumstances, accumulated net operating losses (NOLs) can even serve as the keystone of a successful successor company. However, tax losses are easy to lose without careful planning. Section 382 of the Internal Revenue Code, the section that sets out the rules relating to t ...
... investor losses. In some circumstances, accumulated net operating losses (NOLs) can even serve as the keystone of a successful successor company. However, tax losses are easy to lose without careful planning. Section 382 of the Internal Revenue Code, the section that sets out the rules relating to t ...

original Powerpoint file
... approaches to value a business and we will estimate the value employing a good rule of thumb By the end of our session you will understand the basic steps required to calculate the value of a business….Valuation is both an Art and a Science We will discuss the nuances of valuing businesses; includin ...
... approaches to value a business and we will estimate the value employing a good rule of thumb By the end of our session you will understand the basic steps required to calculate the value of a business….Valuation is both an Art and a Science We will discuss the nuances of valuing businesses; includin ...

Solvay Business School
... at the end of this year is € 800,000. This investment could be depreciated for tax purposes straight-line over 4 years. EuroCorp expects to terminate the project at the end of 4 years. The resale value of the machine will then be zero. The project will require an additional investment in working cap ...
... at the end of this year is € 800,000. This investment could be depreciated for tax purposes straight-line over 4 years. EuroCorp expects to terminate the project at the end of 4 years. The resale value of the machine will then be zero. The project will require an additional investment in working cap ...

Joint stock company
... turnover or price decreases, financial condition of the Company will worsen. Market risk Unpredictability of sales amounts in longer term, price fluctuations of precious metals on the global market, currency fluctuations, especially LVL/USD, LVL/EUR, USD/EUR and quality of precious scrap metal; and ...
... turnover or price decreases, financial condition of the Company will worsen. Market risk Unpredictability of sales amounts in longer term, price fluctuations of precious metals on the global market, currency fluctuations, especially LVL/USD, LVL/EUR, USD/EUR and quality of precious scrap metal; and ...