

Accounting
... course is designed for MBA and MPA students who have not had ACCT 303 or its equivalent. Prerequisite: This course is not open to students who have taken ACCT 303 or its equivalent. ACCT 640 Financial Reporting and Statement Analysis (4) This course examines how generally accepted accounting princip ...
... course is designed for MBA and MPA students who have not had ACCT 303 or its equivalent. Prerequisite: This course is not open to students who have taken ACCT 303 or its equivalent. ACCT 640 Financial Reporting and Statement Analysis (4) This course examines how generally accepted accounting princip ...
CJAR Fundamentalist Perspective on Accounting Jiang
... Abstract. This paper presents a framework for addressing normative accounting issues for reporting to shareholders. The framework is an alternative to the emerging Conceptual Framework of the International Accounting Standards Board and the Financial Accounting Standards Board. The framework can be ...
... Abstract. This paper presents a framework for addressing normative accounting issues for reporting to shareholders. The framework is an alternative to the emerging Conceptual Framework of the International Accounting Standards Board and the Financial Accounting Standards Board. The framework can be ...

Do Firms` Intrinsically Determined Enterprise Values Corroborate
... part of the industry. While the study rued that valuations became more accurate when trailing earnings were substituted with predictive earnings, the absence of consideration a more firm wide representative multiple renders the study somewhat ineffective (Kim & Ritter, 1999). In an intersting study ...
... part of the industry. While the study rued that valuations became more accurate when trailing earnings were substituted with predictive earnings, the absence of consideration a more firm wide representative multiple renders the study somewhat ineffective (Kim & Ritter, 1999). In an intersting study ...

Title: Arial Narrow, size 28 on 1 or 2 lines
... Securities Services and its subsidiaries shall not be liable for any errors, omissions or opinions contained within this document. This material is not intended as an offer or solicitation for the purchase or sale of any financial instrument. For the avoidance of doubt, any information contained wit ...
... Securities Services and its subsidiaries shall not be liable for any errors, omissions or opinions contained within this document. This material is not intended as an offer or solicitation for the purchase or sale of any financial instrument. For the avoidance of doubt, any information contained wit ...

[in the value of the land] due to adjacent capital activity is recorded
... AEG arguments for recording as OCVA • The price of land is not only determined by the economic use, location, size, but also by surrounding amenities which, therefore, should be considered quality elements • When these surrounding amenities change the adjacent land changes simultaneously. These ext ...
... AEG arguments for recording as OCVA • The price of land is not only determined by the economic use, location, size, but also by surrounding amenities which, therefore, should be considered quality elements • When these surrounding amenities change the adjacent land changes simultaneously. These ext ...
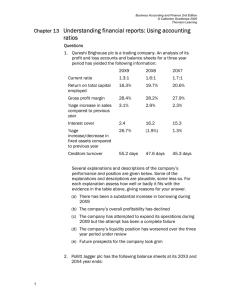
Chapter 13 Understanding financial reports: Using accounting ratios
... Profit after taxation Dividends Profit for the financial year (c) Report to Russ ...
... Profit after taxation Dividends Profit for the financial year (c) Report to Russ ...

Lower Valley Operation RoundUp, Inc
... Farm income Disability income Welfare Alimony Child support Other Income ...
... Farm income Disability income Welfare Alimony Child support Other Income ...

REIT Valuation - Real Estate Society
... If they pay out all their income as dividends, what are the current yields of these two REITs? Why is Sioux a “growth REIT”?… Is ...
... If they pay out all their income as dividends, what are the current yields of these two REITs? Why is Sioux a “growth REIT”?… Is ...

Unit 11 Accounting concepts URS
... Learning Outcome 3: Be able to prepare the principal documents in business transactions M2: Compare the accounting procedures for cash and trade discounts Learning Outcome 4: Be able to use basic double entry bookkeeping to ...
... Learning Outcome 3: Be able to prepare the principal documents in business transactions M2: Compare the accounting procedures for cash and trade discounts Learning Outcome 4: Be able to use basic double entry bookkeeping to ...


IFRS Week Financial Instruments Presentation and
... financial instruments used by an enterprise and how they affect the financial position, performance and cash flows Emphasises on classification of instruments as liabilities or equity. Shift focus from legal form to substance form Example is issue of redeemable preference shares which legally they m ...
... financial instruments used by an enterprise and how they affect the financial position, performance and cash flows Emphasises on classification of instruments as liabilities or equity. Shift focus from legal form to substance form Example is issue of redeemable preference shares which legally they m ...

Acc Plus Aut09
... usually achieved via legal rights but that is not a necessary condition. Future economic benefits This can include revenue from the sale of products or services, cost savings or other benefits resulting from the use of the asset e.g. use of intellectual property may reduce ...
... usually achieved via legal rights but that is not a necessary condition. Future economic benefits This can include revenue from the sale of products or services, cost savings or other benefits resulting from the use of the asset e.g. use of intellectual property may reduce ...

Chapter One
... Students can readily grasp that there is very little profit risk from an interest rate change on the $34 of NEA financed by equity. Likewise there is little profit risk from the $206 FRAs financed by FRLs because the cash inflows and outflows on these accounts do not change over the given maturity b ...
... Students can readily grasp that there is very little profit risk from an interest rate change on the $34 of NEA financed by equity. Likewise there is little profit risk from the $206 FRAs financed by FRLs because the cash inflows and outflows on these accounts do not change over the given maturity b ...

The Implications of Behavioural Finance for the
... values when perturbed by noisy, irrational traders. However, in order to say more about the structure of these deviations and thus make sharper predictions, one needs to specify the exact form of agents’ irrationality. This means how real-world investors actually form their beliefs and valuations, a ...
... values when perturbed by noisy, irrational traders. However, in order to say more about the structure of these deviations and thus make sharper predictions, one needs to specify the exact form of agents’ irrationality. This means how real-world investors actually form their beliefs and valuations, a ...

***** 1
... When a other financial asset or financial liability is recognized initially, an entity shall measure it at its fair value, which is normally the transaction price. Subsequently, at the end of each reporting period an entity shall measure all other financial instruments at fair value and recognize ...
... When a other financial asset or financial liability is recognized initially, an entity shall measure it at its fair value, which is normally the transaction price. Subsequently, at the end of each reporting period an entity shall measure all other financial instruments at fair value and recognize ...

International Business Chapter 18 International Accounting Issues 1
... 16) German companies like Deutsche Bank and Daimler Chrysler have been relatively optimistic and transparent in their financial reporting compared with many Germanic companies because ________. A) German accounting standards have always been optimistic and transparent B) they adopted U.S. Generally ...
... 16) German companies like Deutsche Bank and Daimler Chrysler have been relatively optimistic and transparent in their financial reporting compared with many Germanic companies because ________. A) German accounting standards have always been optimistic and transparent B) they adopted U.S. Generally ...

Still No One Wants to Play
... Rising commodity prices Tightening monetary policy Rising inflation expectations Increasing long-term interest rates Increasing investor optimism. RBA’s portfolios are positioned for a late-cycle environment. This report outlines some of the factors we have considered. The late cycle The economy see ...
... Rising commodity prices Tightening monetary policy Rising inflation expectations Increasing long-term interest rates Increasing investor optimism. RBA’s portfolios are positioned for a late-cycle environment. This report outlines some of the factors we have considered. The late cycle The economy see ...

CONVENTIONAL HUMAN ASSET ACCOUNTING TREATMENT
... significance. For instance, in hospitals, academic institutions, consulting firms etc, the total worth of the organization depends mainly on the skills of its employees and the service they render. Hence, the success of these organizations is contingent on the quality of their human asset – its know ...
... significance. For instance, in hospitals, academic institutions, consulting firms etc, the total worth of the organization depends mainly on the skills of its employees and the service they render. Hence, the success of these organizations is contingent on the quality of their human asset – its know ...

Statement of Risk - ACT Department of Treasury
... The Territory’s financial investments include some diversification across the domestic money and capital markets including cash, short-term debt instruments (maturity less than twelve months) and fixed interest bonds (maturity greater than twelve months), each of which has its own unique risk/return ...
... The Territory’s financial investments include some diversification across the domestic money and capital markets including cash, short-term debt instruments (maturity less than twelve months) and fixed interest bonds (maturity greater than twelve months), each of which has its own unique risk/return ...

Slide 1
... company was credited with 500 in 07-08 on exchange difference and amortized with 175, 325 and 425 during 08-09, 09-10 and 10-11 respectively. On date of transition, the FCTDA account shall not appear in the opening IFRS statement and the effect goes to equity account. As IFRS comparatives for 10-11 ...
... company was credited with 500 in 07-08 on exchange difference and amortized with 175, 325 and 425 during 08-09, 09-10 and 10-11 respectively. On date of transition, the FCTDA account shall not appear in the opening IFRS statement and the effect goes to equity account. As IFRS comparatives for 10-11 ...

ACCOUNTING 201 - Everett Community College
... Grayton-Smith Industries purchased supplies for $1,000. They paid $500 in cash and agreed to pay the balance in 30 days. The journal entry to record this transaction would include a debit to an asset account for $1,000, a credit to a liability account for $500. Which of the following would be the co ...
... Grayton-Smith Industries purchased supplies for $1,000. They paid $500 in cash and agreed to pay the balance in 30 days. The journal entry to record this transaction would include a debit to an asset account for $1,000, a credit to a liability account for $500. Which of the following would be the co ...

Notes on Finite State Approach to Modern Portfolio
... we could define two states of the world: (i) it is raining; (ii) it is not raining. Obviously, there are more than two states regarding the weather. But, how many states we identify will depend upon the problem that we are working on. If we are trying to decide whether to put on rain gear when leavi ...
... we could define two states of the world: (i) it is raining; (ii) it is not raining. Obviously, there are more than two states regarding the weather. But, how many states we identify will depend upon the problem that we are working on. If we are trying to decide whether to put on rain gear when leavi ...
