
Ch6_6exam
... How much did I. M. Farmer's equity increase or decrease during 2007? $ _______________ ...
... How much did I. M. Farmer's equity increase or decrease during 2007? $ _______________ ...

Concepts - 18 SFAC No. 6
... Assets: “Business resources that have probable future economic benefits.” Liabilities: “Probable future sacrifices of economic benefits.” ...
... Assets: “Business resources that have probable future economic benefits.” Liabilities: “Probable future sacrifices of economic benefits.” ...

book keeping & accounting system in islam
... • The emergence of Islamic banks and other financial institutions in 1970s have stimulated modern literatures that have identified ways of addressing Islamic accounting. The increase in financial crime, misappropriation of fund and several corporate scandals and failure in recent past has put more p ...
... • The emergence of Islamic banks and other financial institutions in 1970s have stimulated modern literatures that have identified ways of addressing Islamic accounting. The increase in financial crime, misappropriation of fund and several corporate scandals and failure in recent past has put more p ...

Daimler International Finance B.V. Interim Report 2015
... accounting is applied). The fair value of natural hedges as at 31 December 2014: € 0.1 million and € -3.7 million respectively. ...
... accounting is applied). The fair value of natural hedges as at 31 December 2014: € 0.1 million and € -3.7 million respectively. ...

FINANCIAL STATEMENTS DECEMBER 31, 2015 toge
... U.S. generally accepted accounting principles establish a hierarchy for inputs used in measuring fair value that maximizes the use of observable inputs and minimizes the use of unobservable inputs by requiring that the most observable inputs be used when available. Level 1 within the hierarchy state ...
... U.S. generally accepted accounting principles establish a hierarchy for inputs used in measuring fair value that maximizes the use of observable inputs and minimizes the use of unobservable inputs by requiring that the most observable inputs be used when available. Level 1 within the hierarchy state ...

www.topproducerwebsite.com
... Additional information is available on request. The material contained herein has been prepared from sources and data we believe to be reliable, but we make no guarantee as to its accuracy or completeness. This material is published solely for informational purposes and is not an offer to buy or sel ...
... Additional information is available on request. The material contained herein has been prepared from sources and data we believe to be reliable, but we make no guarantee as to its accuracy or completeness. This material is published solely for informational purposes and is not an offer to buy or sel ...

introduction to the financial statements
... Derivative financial instruments are recognized initially at cost. Subsequent to initial recognition, derivative financial instruments are stated at fair value. The Company does not apply hedge accounting and any gain or loss relating to the change in the fair value of the derivative financial instr ...
... Derivative financial instruments are recognized initially at cost. Subsequent to initial recognition, derivative financial instruments are stated at fair value. The Company does not apply hedge accounting and any gain or loss relating to the change in the fair value of the derivative financial instr ...


effas - Finmedia
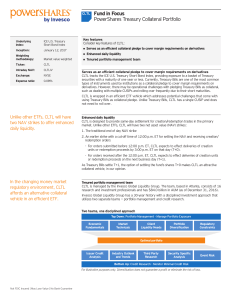
... Overall aim is to set standards for investment professionals in communication, ethics and qualification; to bring influence on EU guidelines and to recognise/respect regional market characteristics. ...
... Overall aim is to set standards for investment professionals in communication, ethics and qualification; to bring influence on EU guidelines and to recognise/respect regional market characteristics. ...

C-68 - IIROC
... above would produce either a capital deficiency or a violation of the Early Warning ByLaw, the member must report the over concentration situation to the Director of Compliance, on the date the over concentration first occurs. IDA By-Law 17.1 requires members to maintain at all times risk adjusted c ...
... above would produce either a capital deficiency or a violation of the Early Warning ByLaw, the member must report the over concentration situation to the Director of Compliance, on the date the over concentration first occurs. IDA By-Law 17.1 requires members to maintain at all times risk adjusted c ...

Clean Tech - GreenWorld Capital, LLC
... quantity of stock at set intervals of time at future stock prices. An effective registration statement must be maintained in order for take downs to be completed. ...
... quantity of stock at set intervals of time at future stock prices. An effective registration statement must be maintained in order for take downs to be completed. ...



chapter 2
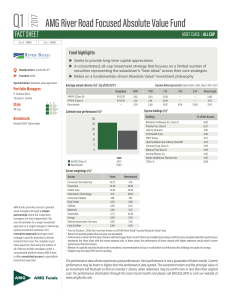
... is focused on the results of business transactions with customers. Economic inflow from the customer is termed revenue, sales, or fees earned. The cost of satisfying customer demands (economic outflow) is termed expense. The income statement details the revenues and expenses of the business, usually ...
... is focused on the results of business transactions with customers. Economic inflow from the customer is termed revenue, sales, or fees earned. The cost of satisfying customer demands (economic outflow) is termed expense. The income statement details the revenues and expenses of the business, usually ...
All findings, interpretations, and conclusions of this presentation
... All findings, interpretations, and conclusions of this presentation represent the views of the author(s) and not those of the Wharton School or the Pension Research Council. © 2008 Pension Research Council of the Wharton School of the University of Pennsylvania. All rights reserved. ...
... All findings, interpretations, and conclusions of this presentation represent the views of the author(s) and not those of the Wharton School or the Pension Research Council. © 2008 Pension Research Council of the Wharton School of the University of Pennsylvania. All rights reserved. ...

Date of Submission: 17-11-2014 FIN 460 Section: 02 Submitted by
... 1. ‘BLI Securities Ltd.’ maintains Margin A/C for their clients. A client of ‘BLI Securities Ltd.’ can borrow Tk. 500,000 minimum from Margin A/C. But the maximum limit is not defined. 2. ‘BLI Securities Ltd.’ does not provide it’s investors any privilege of borrowing loans for personal purpose from ...
... 1. ‘BLI Securities Ltd.’ maintains Margin A/C for their clients. A client of ‘BLI Securities Ltd.’ can borrow Tk. 500,000 minimum from Margin A/C. But the maximum limit is not defined. 2. ‘BLI Securities Ltd.’ does not provide it’s investors any privilege of borrowing loans for personal purpose from ...


PSA 510: Initial Engagements * Opening Balances
... consistently applied or changes in accounting policies have been properly accounted for and adequately disclosed. ...
... consistently applied or changes in accounting policies have been properly accounted for and adequately disclosed. ...

iShares US Treasury Bond 7-10 Year JPY Hedged ETF
... - Because ETFs invest in securities whose prices fluctuate, the market price or base value may decrease due to shifts in the underling index or foreign exchange market, fluctuations in the price of constituent securities, bankruptcy or deterioration in the financial conditions of constituent securit ...
... - Because ETFs invest in securities whose prices fluctuate, the market price or base value may decrease due to shifts in the underling index or foreign exchange market, fluctuations in the price of constituent securities, bankruptcy or deterioration in the financial conditions of constituent securit ...

victory rs large cap alpha fund
... return and principal value will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than the original cost. To obtain performance information current to the most recent month-end, visit www.vcm.com. Investment returns reflect total fund operating expenses, net of all fee ...
... return and principal value will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than the original cost. To obtain performance information current to the most recent month-end, visit www.vcm.com. Investment returns reflect total fund operating expenses, net of all fee ...