
Finance Notes 2008 Size: 351.5kb Last modified
... Economic Model of the Firm: Firms compete in two markets, product markets for customers and financial markets for capital. They trade at two difference prices within financial markets, a lower passive intrinsic value and a higher control price. ...
... Economic Model of the Firm: Firms compete in two markets, product markets for customers and financial markets for capital. They trade at two difference prices within financial markets, a lower passive intrinsic value and a higher control price. ...

ANALYZING SECURITIES INVESTMENT TRUSTS TRADED IN BIST
... ANALYZING SECURITIES INVESTMENT TRUSTS TRADED IN BIST VIA AHPPROMETHEE METHODOLOGY ...
... ANALYZING SECURITIES INVESTMENT TRUSTS TRADED IN BIST VIA AHPPROMETHEE METHODOLOGY ...


1. Without the participation of financial intermediaries in financial
... 46. Investors sell a security short when they expect the price of the security to (Points: 6) increase substantially. ...
... 46. Investors sell a security short when they expect the price of the security to (Points: 6) increase substantially. ...

Should `Minority Discounts` Diminish Share Value Under Judicial
... (1) the discounted income approach, by which average corporate earnings measured over a number of years are capitalized and a multiplier is developed using the capitalization rate which is then applied to earnings; (2) capitalization of dividends, if the corporation has an appropriate dividend histo ...
... (1) the discounted income approach, by which average corporate earnings measured over a number of years are capitalized and a multiplier is developed using the capitalization rate which is then applied to earnings; (2) capitalization of dividends, if the corporation has an appropriate dividend histo ...

Noncontrolling Interest - McGraw Hill Higher Education
... Any resulting gain or loss from the remeasurement should be recognized in the parent’s net income. ...
... Any resulting gain or loss from the remeasurement should be recognized in the parent’s net income. ...
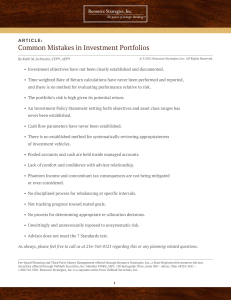
Common Mistakes in Investment Portfolios
... • Time weighted Rate of Return calculations have never been performed and reported, and there is no method for evaluating performance relative to risk. • The portfolio’s risk is high given its potential return. • An Investment Policy Statement setting forth objectives and asset class ranges has n ...
... • Time weighted Rate of Return calculations have never been performed and reported, and there is no method for evaluating performance relative to risk. • The portfolio’s risk is high given its potential return. • An Investment Policy Statement setting forth objectives and asset class ranges has n ...

Boston Partners Large Cap Value Equity
... Investment Advisers Act of 1940. Boston Partners is a subsidiary of Robeco Groep N.V. (“Robeco”), a Dutch investment management firm headquartered in Rotterdam, the Netherlands. Boston Partners updated its firm description as of January 1, 2015 to reflect changes in its divisional structure. Boston ...
... Investment Advisers Act of 1940. Boston Partners is a subsidiary of Robeco Groep N.V. (“Robeco”), a Dutch investment management firm headquartered in Rotterdam, the Netherlands. Boston Partners updated its firm description as of January 1, 2015 to reflect changes in its divisional structure. Boston ...

Summary Accounts - Friends of Salisbury Cathedral
... Respective Responsibilities of Members of the Executive Council and Auditors We have examined the summarised accounts , consisting of the summarised Statement of Financial Activities and Balance Sheet, which are the responsibility of the members of the Executive Council. Our responsibility is to rep ...
... Respective Responsibilities of Members of the Executive Council and Auditors We have examined the summarised accounts , consisting of the summarised Statement of Financial Activities and Balance Sheet, which are the responsibility of the members of the Executive Council. Our responsibility is to rep ...
Slides - WordPress.com
... Typically when another financing is anticipated Note attracts interest (10-15%) and a discount (20-40%) on next round (*if* the next round investor is sympathetic) – PLUS typical terms required by the investor e.g. liquidation pref ...
... Typically when another financing is anticipated Note attracts interest (10-15%) and a discount (20-40%) on next round (*if* the next round investor is sympathetic) – PLUS typical terms required by the investor e.g. liquidation pref ...

required rate of return2
... – Most models of default risk use financial ratios to measure the cash flow coverage (magnitude of the cash flows relative to the obligation) and control for industry effects in order to evaluate the variability of the cash flows. – The most widely used measure of a firm’s default risk is its ...
... – Most models of default risk use financial ratios to measure the cash flow coverage (magnitude of the cash flows relative to the obligation) and control for industry effects in order to evaluate the variability of the cash flows. – The most widely used measure of a firm’s default risk is its ...

Institute of Actuaries of India INDICATIVE SOLUTIONS November 2012 Examinations
... calculates the average price of the MBS. Valuation measure of MBS/CMO The yield spread, the standard measure of incremental return over a benchmark Treasury, is inappropriate valuation measure as it compares an MBS/CMO to a single, somewhat arbitrarily chosen point on the yield curve. Because an MBS ...
... calculates the average price of the MBS. Valuation measure of MBS/CMO The yield spread, the standard measure of incremental return over a benchmark Treasury, is inappropriate valuation measure as it compares an MBS/CMO to a single, somewhat arbitrarily chosen point on the yield curve. Because an MBS ...

Credit Union Merger Accounting Guidance
... How is the core deposit intangible calculated? The premise underlying the core deposit intangible is that a rational buyer is willing to pay a premium to obtain a group of core deposit accounts that are less expensive than the buyer’s marginal cost of funds. The value is determined through a discou ...
... How is the core deposit intangible calculated? The premise underlying the core deposit intangible is that a rational buyer is willing to pay a premium to obtain a group of core deposit accounts that are less expensive than the buyer’s marginal cost of funds. The value is determined through a discou ...

CL 07 - ED IFRS for SMEs - OIC
... be sufficient to require that the residual value be adjusted only when there is objective evidence to believe that it has been significantly modified (reduced). Thus, there is no need for the calculation ...
... be sufficient to require that the residual value be adjusted only when there is objective evidence to believe that it has been significantly modified (reduced). Thus, there is no need for the calculation ...

Random Variables A random variable, X, represents a numerical
... Based on the expected value of each, which investment should you make? ...
... Based on the expected value of each, which investment should you make? ...

Terms of Sale
... A firm that buys on credit is in effect borrowing from its supplier. It saves cash today but will have to pay later. This, of course, is an implicit loan from the supplier. We can calculate the implicit cost of this loan ...
... A firm that buys on credit is in effect borrowing from its supplier. It saves cash today but will have to pay later. This, of course, is an implicit loan from the supplier. We can calculate the implicit cost of this loan ...

ETF Strategists: The Next Generation of Asset Allocation
... 1. What role will the strategy play in your client’s portfolio? Will it be used for return enhancement, diversification, or risk management? Some advisers use tactical asset allocators to supplement a core portfolio, while others use them as a core holding. Having a clear purpose simplifies the de ...
... 1. What role will the strategy play in your client’s portfolio? Will it be used for return enhancement, diversification, or risk management? Some advisers use tactical asset allocators to supplement a core portfolio, while others use them as a core holding. Having a clear purpose simplifies the de ...

Define and Discuss on Stock Terminology
... investment of the preferred stockholders was returned to them. It may have a par value or be no‐par value stock that may or may not have a stated value. Preferred stock. Preferred stock is a class of stock that normally has the right to receive dividends, and in the case of liquidation of the corpor ...
... investment of the preferred stockholders was returned to them. It may have a par value or be no‐par value stock that may or may not have a stated value. Preferred stock. Preferred stock is a class of stock that normally has the right to receive dividends, and in the case of liquidation of the corpor ...

Examples of CIPM Principles Exam Questions
... Expressed as a percentage of total firm assets, the size of the large cap equity composite is closest to: A. 18.5%. B. 24.7%. C. 25.4%. 13. The Brook Corporation writes a letter informing its equity manager, Caribou Asset Management, that the prohibition against using derivative securities has been ...
... Expressed as a percentage of total firm assets, the size of the large cap equity composite is closest to: A. 18.5%. B. 24.7%. C. 25.4%. 13. The Brook Corporation writes a letter informing its equity manager, Caribou Asset Management, that the prohibition against using derivative securities has been ...

EXECUTIVE BOARD MEETING MINUTES Tuesday, August 9, 2016
... NCPC Investment Accounts: See attached summary for additional details. Basic Checking Account – recommendation is to leave it. Money Market Savings Account – recommendation is to move it to a standard savings account. CDs – current balance is approximate $36K. We continue to lose money on the ...
... NCPC Investment Accounts: See attached summary for additional details. Basic Checking Account – recommendation is to leave it. Money Market Savings Account – recommendation is to move it to a standard savings account. CDs – current balance is approximate $36K. We continue to lose money on the ...
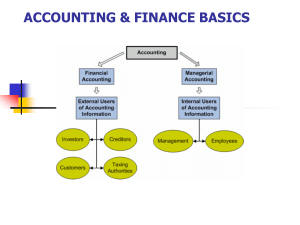
WIS ACCOUNTING BASICS
... at a specific date. A balance sheet is also called Statement of Financial Position. A cash flow statement summarizes information about cash outflows (payments) and inflows (receipts). This statement may also include certain information not related to actual cash flows. ...
... at a specific date. A balance sheet is also called Statement of Financial Position. A cash flow statement summarizes information about cash outflows (payments) and inflows (receipts). This statement may also include certain information not related to actual cash flows. ...

Investment Policy Money Market Funds Rpt
... This report provides the Committee with information concerning Money Market Funds (MMF) and seeks the Committee’s approval to use them as outlined in the revised Investment Policy approved by this Committee on 16 September 2010. ...
... This report provides the Committee with information concerning Money Market Funds (MMF) and seeks the Committee’s approval to use them as outlined in the revised Investment Policy approved by this Committee on 16 September 2010. ...

Debt (B) Value of firm (V)
... a Changes in short-term borrowing are shown under net increase in debt. "Other uses" are net of any increase in miscellaneous liabilities and any statistical discrepancy. b Net income plus depreciation less cash dividends paid to stockholders Source: Board of Governors of the Federal Reserve System, ...
... a Changes in short-term borrowing are shown under net increase in debt. "Other uses" are net of any increase in miscellaneous liabilities and any statistical discrepancy. b Net income plus depreciation less cash dividends paid to stockholders Source: Board of Governors of the Federal Reserve System, ...

Print Stock Gifting Instructions Here
... power of your charitable contributions, consider donating your long-term appreciated securities to Gannon University. Benefits of gifting appreciated securities to Gannon University Donating long-term appreciated securities directly to Gannon University, rather than selling the assets and donating t ...
... power of your charitable contributions, consider donating your long-term appreciated securities to Gannon University. Benefits of gifting appreciated securities to Gannon University Donating long-term appreciated securities directly to Gannon University, rather than selling the assets and donating t ...

HSBC Money Market Fund
... funds is not a deposit of HSBC Bank USA, N.A. and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. The funds’ sponsor has no legal obligation to provide financial support to the funds, and you should not expect that the sponsor will provide fi ...
... funds is not a deposit of HSBC Bank USA, N.A. and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. The funds’ sponsor has no legal obligation to provide financial support to the funds, and you should not expect that the sponsor will provide fi ...