
Claim for Securities
... account, unless: (1) The Debtor has sent written confirmation to the customer that the securities in question have been sold for or purchased from the customer’s account; or (2) Whether or not written confirmation of the purchase has been sent, if the securities in question have become the subject ...
... account, unless: (1) The Debtor has sent written confirmation to the customer that the securities in question have been sold for or purchased from the customer’s account; or (2) Whether or not written confirmation of the purchase has been sent, if the securities in question have become the subject ...

METLIFE FIDELITY CORPORATE BOND FUND 16 YEAR
... The fund aims to provide a level of income and capital growth over the long term. The fund primarily has exposure to investment grade corporate bonds, hedged back to sterling but also to bonds issued by governments and other bodies. The fund’s interest rate sensitivity is adjusted to ten years throu ...
... The fund aims to provide a level of income and capital growth over the long term. The fund primarily has exposure to investment grade corporate bonds, hedged back to sterling but also to bonds issued by governments and other bodies. The fund’s interest rate sensitivity is adjusted to ten years throu ...


Chapter 7 PPP
... its assets. Leverage Ratios: amount of debt used by the company. Profitability Ratios: measures how successful the company is at ...
... its assets. Leverage Ratios: amount of debt used by the company. Profitability Ratios: measures how successful the company is at ...


PDF
... where all of the above are discounted for transaction cost and dividend payments. The intrinsic value at time t doeg not involve a specific period within the plannin~:horizont The derivation of this expected price by the investor can be considered in either of two ways: ...
... where all of the above are discounted for transaction cost and dividend payments. The intrinsic value at time t doeg not involve a specific period within the plannin~:horizont The derivation of this expected price by the investor can be considered in either of two ways: ...


the investment position of the major players in the ukrainian`s grain
... – land in Ukraine. * As of 30 June 2012, 40,000 ha are subject to antitrust clearance. The Company holds an option to purchase another 79,200 ha of leasehold farmland. Shares of «LTD Kernel» are the part of the Polish stock index WIG20 of Warsaw Stock Exchange (WSE) with a weight of 2,4%, and a good ...
... – land in Ukraine. * As of 30 June 2012, 40,000 ha are subject to antitrust clearance. The Company holds an option to purchase another 79,200 ha of leasehold farmland. Shares of «LTD Kernel» are the part of the Polish stock index WIG20 of Warsaw Stock Exchange (WSE) with a weight of 2,4%, and a good ...
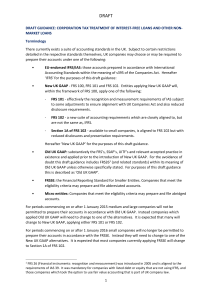
Corporation Tax treatment of interest-free loans and other
... The guidance at CFM33174 onwards addresses some of the most common situations. Proposed changes to the rules for loans and derivatives Note that the government has proposed changes to the taxation of loans and derivatives, which could impact on the treatment of financial instruments entered into on ...
... The guidance at CFM33174 onwards addresses some of the most common situations. Proposed changes to the rules for loans and derivatives Note that the government has proposed changes to the taxation of loans and derivatives, which could impact on the treatment of financial instruments entered into on ...


Why value value? - Spears School of Business
... focus on value creation when nonfinancial business corporations collecmarket prices of shares do not tively held 61.2 percent of listed shares in reflect good information 1983, but engaged in only 10.7 percent of trades. Most institutional shareholding is within the large business groups, the keiret ...
... focus on value creation when nonfinancial business corporations collecmarket prices of shares do not tively held 61.2 percent of listed shares in reflect good information 1983, but engaged in only 10.7 percent of trades. Most institutional shareholding is within the large business groups, the keiret ...

Management 5187 - Baylor University
... source for electricity production. However, several executives think that a wind farm venture would offer valuable diversification benefits. Other executives believe they could exploit the company’s downstream customer channels to efficiently market wind-produced electricity. The Vice President of s ...
... source for electricity production. However, several executives think that a wind farm venture would offer valuable diversification benefits. Other executives believe they could exploit the company’s downstream customer channels to efficiently market wind-produced electricity. The Vice President of s ...


Company OJSC Transcontainer TIDM TRCN Headline Publication
... statements by terms such as "expect," "believe," "anticipate," "estimate," "intend," "will," "could," "may," or "might," or the negative of such terms or other similar expressions. These statements are only predictions and actual events or results may differ materially. The Company does not intend t ...
... statements by terms such as "expect," "believe," "anticipate," "estimate," "intend," "will," "could," "may," or "might," or the negative of such terms or other similar expressions. These statements are only predictions and actual events or results may differ materially. The Company does not intend t ...


(BPM6) and Fourth Edition
... entity or group of related entities that is able to exercise influence over another entity that is resident of a different economy. FDI reflects the objective of gaining control or a significant degree of influence by an entity in one economy over the management of an enterprise resident in another ...
... entity or group of related entities that is able to exercise influence over another entity that is resident of a different economy. FDI reflects the objective of gaining control or a significant degree of influence by an entity in one economy over the management of an enterprise resident in another ...


Transaction Exposure
... Operating (Economic) Exposure – change in firm PV resulting from change in expected future operating cash flows due to unexpected forex change ...
... Operating (Economic) Exposure – change in firm PV resulting from change in expected future operating cash flows due to unexpected forex change ...

Indirect Investing
... intermediaries that hold securities in portfolio ◦ Shares are ownership interest in portfolio entitled to portfolio income ◦ Shareholders also pay expenses and management ...
... intermediaries that hold securities in portfolio ◦ Shares are ownership interest in portfolio entitled to portfolio income ◦ Shareholders also pay expenses and management ...

4Q16 Firm Overview.ind.indd
... Global/international equity Berkeley Street Emerging Markets Equity Boston, MA ...
... Global/international equity Berkeley Street Emerging Markets Equity Boston, MA ...

CHAPTER 02 AA Accounting for Business
... arises when companies wish to raise money from lenders and investors in different countries. International Accounting Standards Board (IASB) ...
... arises when companies wish to raise money from lenders and investors in different countries. International Accounting Standards Board (IASB) ...

Assignment-77 - The complete management portal
... 154) That part of the inventory which does not become a part of final product but are required for production process is termed as=> Stores and supplies 155) The inputs purchased and stored to be converted into finished products, this constitutes investment of inventory in the form of=> Raw Material ...
... 154) That part of the inventory which does not become a part of final product but are required for production process is termed as=> Stores and supplies 155) The inputs purchased and stored to be converted into finished products, this constitutes investment of inventory in the form of=> Raw Material ...

This paper presents a modest contribution to the
... Ch 29, pp 597 – 598).” Therefore when C acquires shares, they are bought with the expectation of future returns (based upon future surplus value), or as finance theory would suggest, based on predictions of the future cash flows and profitability of the business. They can be bought and sold many tim ...
... Ch 29, pp 597 – 598).” Therefore when C acquires shares, they are bought with the expectation of future returns (based upon future surplus value), or as finance theory would suggest, based on predictions of the future cash flows and profitability of the business. They can be bought and sold many tim ...