Adjusting the Black-Scholes Framework in the Presence of a Volatility Skew
AcSB Implementation Guide Hedging Relationships Typescript

Acquisition of Norgani Hotels ASA
ACCT5341 SP05 Exam 1a 031405
ACCOUNTING FOR FINANCIAL INSTRUMENTS
Absolute Dividends

about EURIBOR on 4 pages
Abnormal Returns, Risk, and Options in Large Data Sets
A Two-Asset Jump Diffusion Model with Correlation
A Study of Implied Risk-Neutral Density Functions in
A stochastic control approach to no-arbitrage bounds given
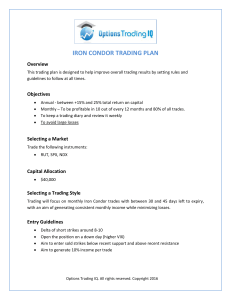
a sample iron condor trading plan here
Automated Transactive Energy

Asset/Liability Management Day 4
ASIC Market Integrity Rules - Federal Register of Legislation

ASIC Market Integrity Rules (Securities Markets – Capital) 2017
Asian basket options and implied correlations in energy
Arbitrage Opportunities in Misspecified Stochastic volatility Models
Applying fuzzy parameters in pricing financial derivatives inspired by
Answer to PP2001
